
Centro de recursos sobre cotizaciones en EE. UU.
Foreign Private Issuer Status: The International Company’s Edge
Parte de la guía de AUM: Salida a bolsa y preparación de las empresas cotizadas
Most companies that come to the U.S. markets from Asia or Europe list as foreign private issuers — and the ones that use the status deliberately save months of work and real money, during the offering and every year after it. FPI status is the single biggest structural advantage an international issuer holds over its U.S.-domiciled peers.
The FPI Test
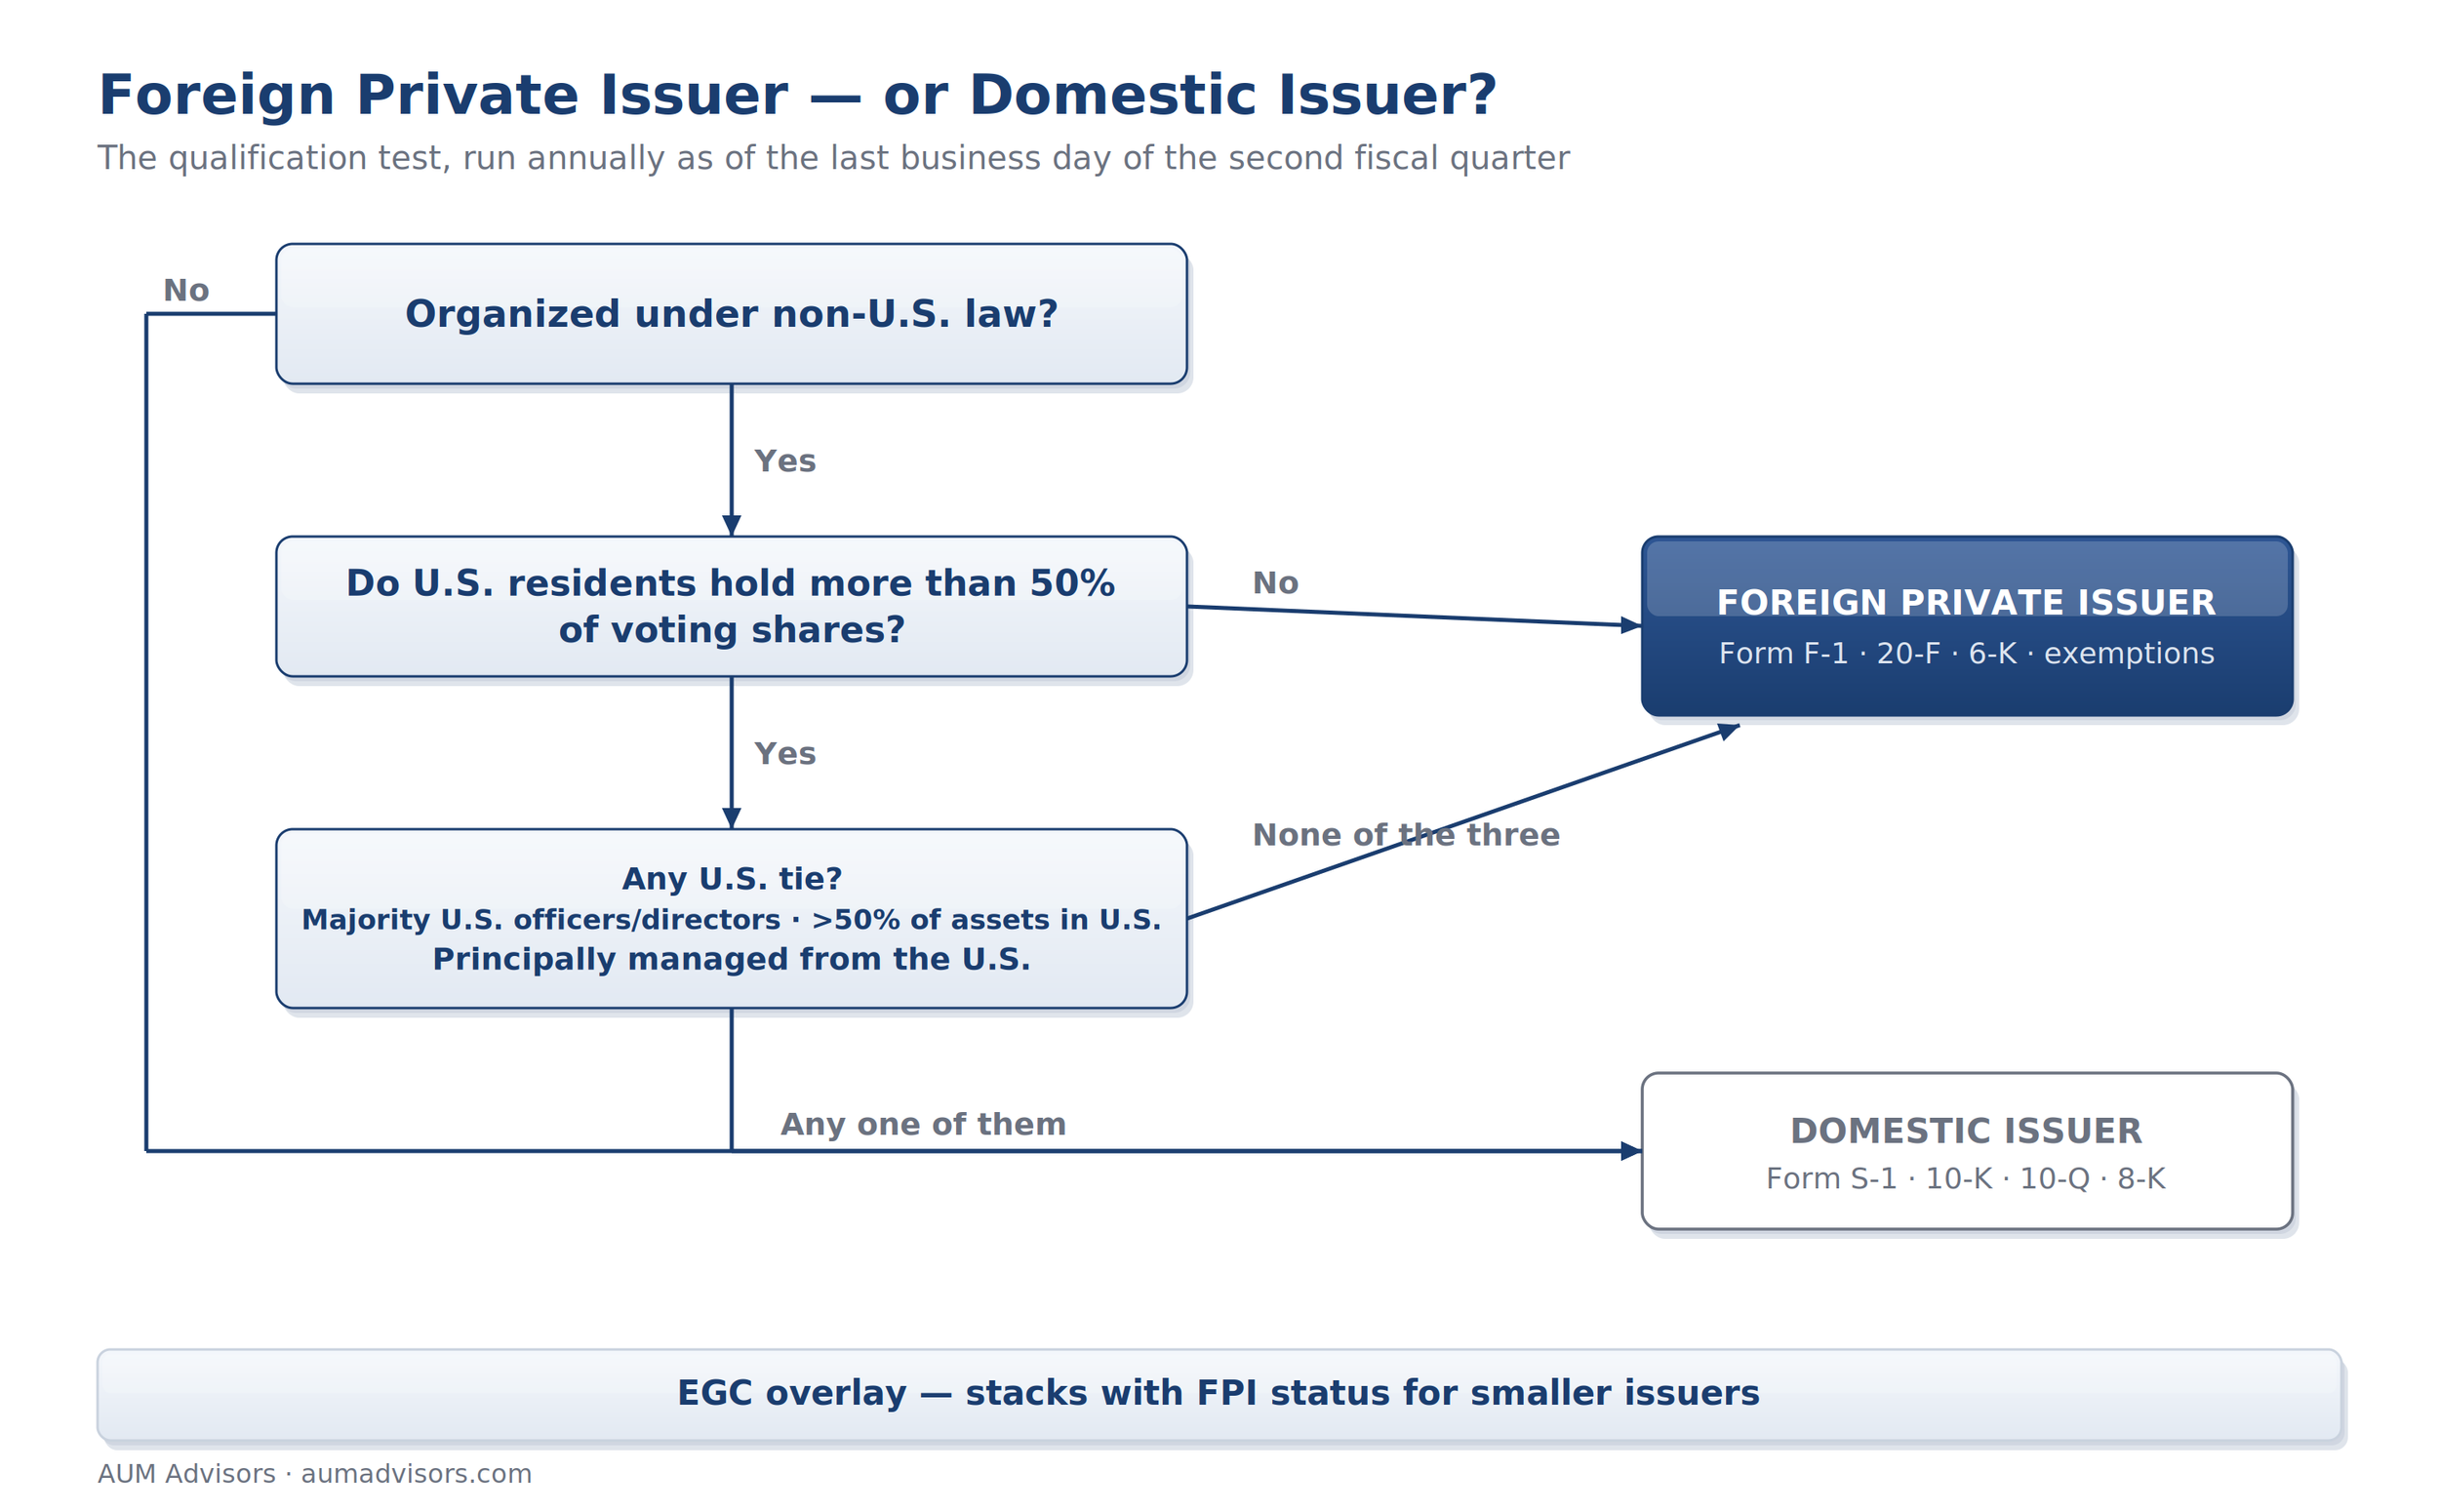
A company organized outside the United States is an FPI unless U.S. residents hold more than 50% of its voting shares. Even then, the status survives unless one of three ties to the U.S. exists: a majority of officers and directors are U.S. citizens or residents, more than half of assets sit in the U.S., or the business is principally administered from the U.S.
The test runs once a year, as of the last business day of the second fiscal quarter — which means status can be lost, and managing the shareholder register and governance footprint is part of keeping it. Most Asian issuers structure through a Cayman Islands or BVI holding company as the listed vehicle; where a VIE structure consolidates the operating business, get the tax and legal opinions early — it is a frequent source of SEC comment and of problems that surface only when a dividend is contemplated.
One caution: the rules here are in motion. The FPI definition itself is under SEC review — a June 2025 concept release asked whether eligibility should be tightened, with foreign companies listed only in the U.S. the population most likely affected. No new definition has been adopted as of October 2026; if the SEC acts, this guide will be updated the week it does. Primary sources: the SEC's concept release and the SEC's overview for foreign private issuers.
What the Status Gets You
- Registration on Form F-1 rather than S-1 — similar content, with relief on certain sensitive disclosures.
- Annual reporting on Form 20-F, due four months after fiscal year-end, versus the far tighter domestic 10-K clock.
- No Form 10-Q and no 8-K regime — material information goes to the market on Form 6-K, on a more limited set of triggers.
- Exemption from U.S. proxy rules — though the historic Section 16 exemption has narrowed. Under the Holding Foreign Insiders Accountable Act and SEC rules adopted February 27, 2026, directors and officers of FPIs with Exchange Act–registered equity now file Section 16(a) ownership reports on Forms 3, 4 and 5 (effective March 18, 2026). The short-swing-profit and short-sale provisions still do not apply, FPI 10% holders remain outside Section 16(a), and 5% beneficial owners report as before — but counsel review before insiders trade is now essential, not merely prudent.
- Explicit exemption from Regulation FD.
- Accounting choice: U.S. GAAP, IFRS as issued by the IASB, or local standards reconciled to U.S. GAAP — and reporting in the currency that fits the business.
- Executive compensation disclosed in aggregate rather than person by person.
- Home-country governance practices in place of most exchange governance rules — the audit committee requirement being the exception Nasdaq and the NYSE will enforce.
The EGC Overlay
Smaller issuers can stack emerging growth company treatment on top:
- confidential submission of the draft registration statement,
- two years of audited financials instead of three,
- testing-the-waters meetings with institutional investors before committing to the full expense of an offering, and
- deferral of the auditor's internal-controls attestation for up to five years.
The revenue ceiling for Emerging Growth Company (EGC) status is inflation-adjusted and is currently $1.235 billion in total annual gross revenues during the company's most recently completed fiscal year. For a company unsure whether the IPO window will hold, confidential filing plus testing the waters is the difference between exploring a listing and announcing one.
The Trap: Exemptions Provide the Floor, Not a Strategy
Everything above describes what an FPI may do, not what a credible management team should do.
Institutional investors benchmark you against U.S.-listed peers who report quarterly, hold earnings calls, and comply with Reg FD — and they discount companies that disclose less. In practice, FPIs that want an institutional following publish quarterly results on 6-K with full financial statements, run a conventional earnings calendar, and follow Reg FD principles voluntarily. The accommodations are for cutting cost and legal exposure — not visibility. Setting that reporting posture, and the disclosure policy behind it, is exactly the work AUM does before a listing prices.
Preguntas frecuentes
When is FPI status tested? Annually, as of the last business day of the second fiscal quarter. A company that fails the test transitions to domestic filer forms on a set schedule — a costly surprise if unplanned.
Do FPIs have to report quarterly? No. Most companies that want institutional investors do so anyway, by choice, on Form 6-K.
Can an FPI also be an EGC? Yes — the statuses stack, and together they define the lightest compliant path to a U.S. listing.
Does FPI status affect valuation? The status doesn't; the behavior it permits can. Report like your U.S. peers and the market treats you like one.
Are the FPI rules changing? In part they already have: since March 18, 2026, directors and officers of FPIs file Section 16(a) ownership reports. The definition itself is under SEC review. We update this guide as rules are adopted.
Recursos relacionados
- La cronología de las salidas a bolsa en EE. UU. — y el equipo que la gestiona
- Tres vías para cotizar en bolsa en EE. UU.
- Guía de cotización para empresas japonesas que estén considerando salir a bolsa en EE. UU.
Structuring a listing as an FPI? Set the reporting posture before the bankers set the timetable.
Habla con AUM